iPAY9 Withdrawals Australia: Payout Checks, KYC and What Is Verified
 Available in AU
Australia payout guide
iPAY9 uses identity verification in its account and withdrawal flow, so a payout request can be affected by KYC or other account checks. What is not safe to publish as a fixed promise is an exact iPAY9 withdrawal minimum, maximum, fee or processing time: current public sources give conflicting figures, and the brand’s own marketing includes speed claims that should not be treated as a guaranteed settlement time. The useful approach is therefore to separate what is verified from what remains unresolved, confirm the live cashier terms before requesting a payout, and keep a clean record of the request if support needs to investigate it.
Table of Contents
- What is verified and what remains unresolved
- A withdrawal request is not the same as money received
- How KYC can affect an iPAY9 payout
- What to save if a payout is delayed
- Using support without losing the transaction trail
- What the current review sample can and cannot tell you
- Build the payout record around events, not a promised clock
- What matters most before requesting an iPAY9 withdrawal
What is verified and what remains unresolved
Withdrawal pages are easy to make misleading because a precise number looks useful even when the evidence behind it is weak. For iPAY9, the strongest current evidence supports the existence of identity verification and several support channels. It does not support one stable public value for every payout limit, fee or settlement time.
The payment methods covers deposit-side methods separately. That distinction matters because a method that can fund an account does not automatically have the same withdrawal rules. The iPAY9 Australia review connects the payout question with games, account access, payments and regulatory context without turning any one banking claim into an overall verdict.
| Payout question | Current evidence | How to use it |
|---|---|---|
| Is identity verification part of the flow? | Yes. Current iPAY9 material includes identity verification in the account flow, and withdrawal-focused material also links verification status to payout handling. | Expect verification to matter, but do not assume a fixed document list or completion time. |
| What is the minimum withdrawal? | Unresolved. Current public sources publish different figures. | Use the amount displayed in the live cashier for the account and method being used. |
| What are the maximum limits? | Unresolved. Public limits vary by source and are sometimes tied to account or VIP status. | Check the current cashier and terms rather than relying on a generic ceiling copied from a review page. |
| How long does a withdrawal take? | No single guaranteed time is safe to state. Current public pages make materially different speed claims. | Treat a request timestamp, approval status and actual bank receipt as separate stages. |
| Are there withdrawal fees? | No stable account-wide fee schedule has been verified for this page. | Read the live withdrawal screen and any payment-provider fee notice before confirming. |
| Can support be contacted? | Yes. Current evidence supports live chat and email, while WhatsApp and Telegram are also listed by multiple Australian-facing sources. | Use the channel shown inside the current account or site and keep the case reference if one is issued. |
A withdrawal request is not the same as money received
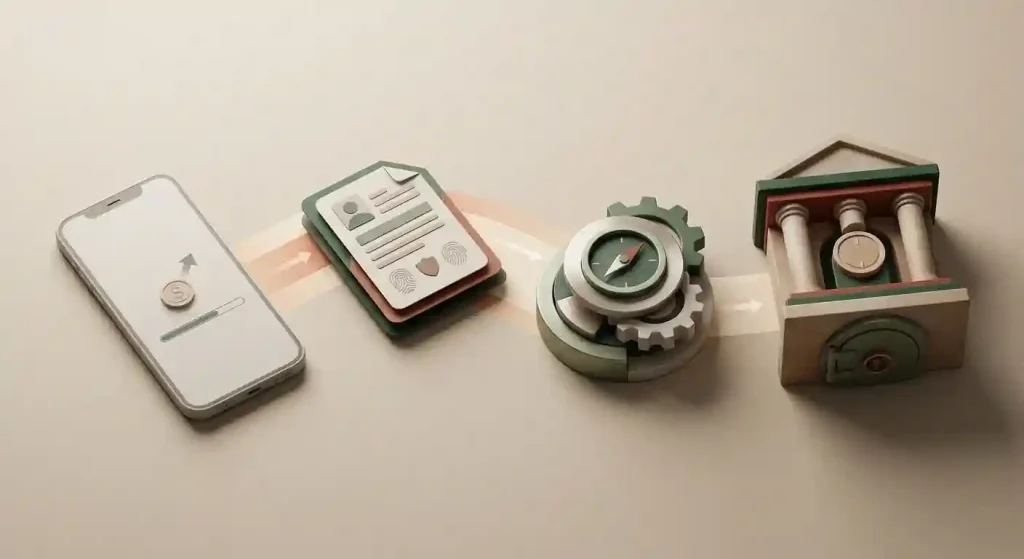
A payout has several stages that are often collapsed into one headline number. First, the account submits the request. The platform may then review the request, account status and identity checks. After approval, the payment still needs to move through the selected payment route before it reaches the destination account.
That is why a marketing line about a fast cash-out should not be read as a guaranteed bank receipt time. Current public sources disagree on the speed and minimums. A more reliable way to track a payout is to record four events: when the request was submitted, whether the account shows it as pending or approved, when the platform says it was sent, and when the destination account actually received it.
This distinction is also useful when comparing payment routes. A bank transfer, card-related route or account-to-account option can have different availability in each direction. If PayID is relevant to funding, the focused PayID deposits explains why deposit support should not be converted into a withdrawal claim.
How KYC can affect an iPAY9 payout
The current evidence supports a simple fact: identity verification is part of iPAY9’s account and/or withdrawal flow. It does not support a fixed public checklist of documents or a promised verification duration for every Australian user. Those details are exactly the kind of high-risk information that can change with account history, payment method and the operator’s current checks.
The practical implication is to make sure the account details are internally consistent before requesting a withdrawal. The name and other details used for the account should match the information attached to the payment route where the platform requires that match. If a verification request appears, follow the current on-screen request rather than an old third-party checklist.
The KYC and registration covers the broader account setup. For payout purposes, the important point is narrower: an unresolved verification check can become a separate step between submitting a withdrawal and seeing it approved.
What to save if a payout is delayed
A good evidence trail is more useful than repeatedly sending the same message to support. It creates a clear timeline and reduces the chance of confusion about which transaction is being discussed.
Request details
Save the withdrawal amount, selected method, request time and any transaction or reference number displayed by the account.
Status changes
Keep dated records of pending, approved, rejected or returned statuses. Avoid including unrelated personal information in anything shared publicly.
Verification messages
Keep the exact wording of any KYC request and note when requested information was supplied. Do not assume an old checklist applies.
Support history
Save chat transcripts, emails and case numbers so a later support contact can follow the same issue without restarting the timeline.
Destination evidence
If the platform says funds were sent, keep the relevant bank or wallet record that shows whether the transfer arrived.
Current terms
Capture the live withdrawal screen or terms that were visible when the request was made, especially any limit, fee or method restriction.
Using support without losing the transaction trail
iPAY9 support is currently described through live chat and email, with WhatsApp and Telegram also listed by multiple Australian-facing sources. The exact contact handle should be taken from the current site or account interface rather than copied from an old review page.
When contacting support, a concise transaction summary is easier to investigate than a long conversation without dates. Include the request reference, the current account status, whether verification is complete or still requested, and the most recent action already taken. Avoid sending identity documents through a channel unless the current platform verification flow specifically directs you there.
If a disagreement becomes a wider trust or protection question, the licence and player protections explains the Australian regulatory context and why local licensing status is separate from a payment method or support channel.
What the current review sample can and cannot tell you
The visible Trustpilot profile for ipay9.com currently contains only two reviews, both tagged to Australian reviewers, and the experiences are mixed. With only two visible reviews, the sample is far too small to measure typical payout performance or support quality.
That makes the reviews useful as anecdotes, not as a statistical conclusion. They show that payout and support are real user concerns, but they do not establish a normal processing time, a normal failure rate or a brand-wide verdict. The current Trustpilot profile should therefore be read as a tiny sample rather than as a substitute for transaction evidence.
Build the payout record around events, not a promised clock
Because the available sources do not support one stable processing time, the most useful record is a sequence of events. Note when the withdrawal was requested, the method selected, any status shown in the account, any verification request, the time support was contacted and the point at which funds were actually received or returned. That creates a transaction-specific timeline without turning one user’s experience into a general payout promise.
The same discipline helps when KYC appears. Keep the exact wording of the current request and the date it was answered, but do not assume that another user’s document list or verification duration applies. If the issue needs escalation, a clear timeline plus the current transaction reference is more informative than repeating a marketing speed claim or an isolated review.
What matters most before requesting an iPAY9 withdrawal
Before submitting a withdrawal, check the live cashier rather than relying on a fixed number from a search result. Confirm the method actually offered for withdrawal, the displayed minimum or limit, any fee notice, and whether the account shows an outstanding verification requirement.
Then keep a simple timeline from request to receipt. iPAY9 does use identity verification, and support channels are available, but the current evidence does not justify promising a specific payout time or publishing one universal withdrawal limit for Australian users. The strongest decision rule is straightforward: trust the current account terms for the transaction, document each stage, and treat marketing speed claims and isolated reviews as secondary evidence rather than guarantees. That keeps the decision tied to the transaction actually being processed.